
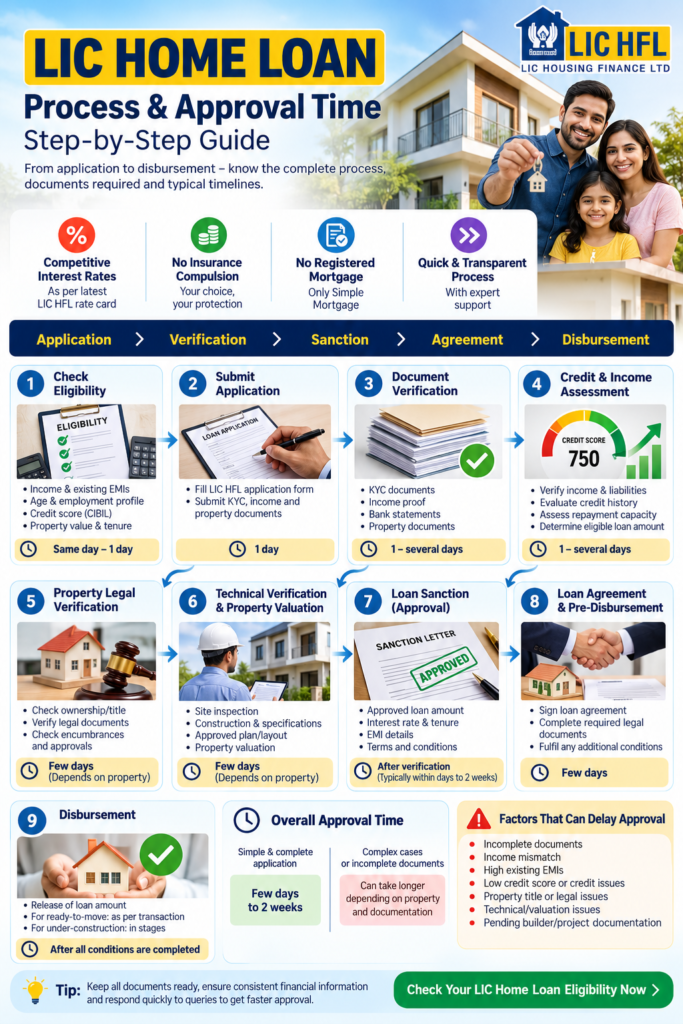
Quick answer: An LIC HFL home loan goes through eight steps: eligibility check, choosing the property, application with documents, LIC HFL’s credit appraisal, legal and technical checks on the property, sanction, signing and MODT, and disbursement. With complete documents it usually takes about two to three weeks from application to disbursement, and less in LIC HFL approved projects.
Updated: October 2026 · By Vijay Arjun, authorised LIC HFL DSA since 2002. Timelines are indicative — the property’s legal check and how quickly documents come in make the biggest difference.
What is the LIC home loan process, step by step?
1. Check your eligibility
Your income, existing EMIs, age and CIBIL score decide how much you can borrow. Our eligibility calculator gives an indicative figure in a minute, and we confirm it before you book a property.
2. Choose the property — and check whether it is LIC HFL approved
In an LIC HFL approved project, the project’s legal and technical checks are already done, which saves time later. For resale homes, plots and other projects, LIC HFL checks the property for your file.
3. Apply with your documents
Submit the application form with KYC, income and property documents, and pay LIC HFL’s processing fee. See the complete documents checklist.
4. LIC HFL’s credit appraisal
LIC HFL verifies your income and employment, checks your CIBIL report and may hold a short discussion with you. This decides the amount, tenure and rate offered.
5. Legal and technical check of the property
A lawyer checks the title chain and approvals; an engineer inspects and values the property. This step takes the longest for resale homes and plots, and is mostly already done in approved projects.
6. Sanction letter
LIC HFL issues the sanction letter with the loan amount, rate, tenure and conditions. Read the conditions carefully — some must be met before disbursement.
7. Agreement, your own contribution and MODT
You sign the loan agreement, pay your own share of the price to the seller or builder, and deposit the original title deeds with LIC HFL under a memorandum of deposit of title deeds (MODT).
8. Disbursement
For a ready or resale home the loan is usually paid in one go at registration. For an under-construction home it is released in stages as construction progresses, and you pay interest only on the amount released until it is complete.
How long does LIC home loan approval take?
| Situation | Usual time from complete application to sanction |
|---|---|
| Flat in an LIC HFL approved project, salaried applicant | About 1 week |
| Resale flat or house | About 2–3 weeks (title and valuation checks) |
| Self-employed applicant | About 2–3 weeks (income assessment) |
| Plot or construction loan | About 2–4 weeks (layout and building approvals) |
Indicative, based on our experience with complete files. Missing documents, title issues or changes in the property are the usual causes of delay.
How can you speed up your LIC home loan?
- Have every applicant’s KYC and income documents ready before you apply.
- Choose an LIC HFL approved project where possible.
- Get the property papers checked before you pay an advance.
- Reply quickly to any query from LIC HFL — we track your file and tell you exactly what is needed.
Frequently asked questions
How do I check my LIC HFL home loan status?
Existing LIC HFL customers can use LIC HFL’s customer services on lichousing.com. If you applied through us, call or WhatsApp us — we follow your file with LIC HFL and update you.
Can I apply for an LIC home loan before choosing a property?
Yes. You can check your eligibility and get your income documents assessed first, so you know your budget before you book.
Why does a resale or plot loan take longer?
Because LIC HFL has to check the property’s full title history, approvals and value for your file, which in an approved project is done in advance.
Do I need to visit the LIC HFL office?
Mostly not when you apply through us — we collect and check your documents and submit the file. You will need to be present to sign the loan documents and for the property registration.
Start now: free eligibility check · LIC HFL home loan in Hyderabad