
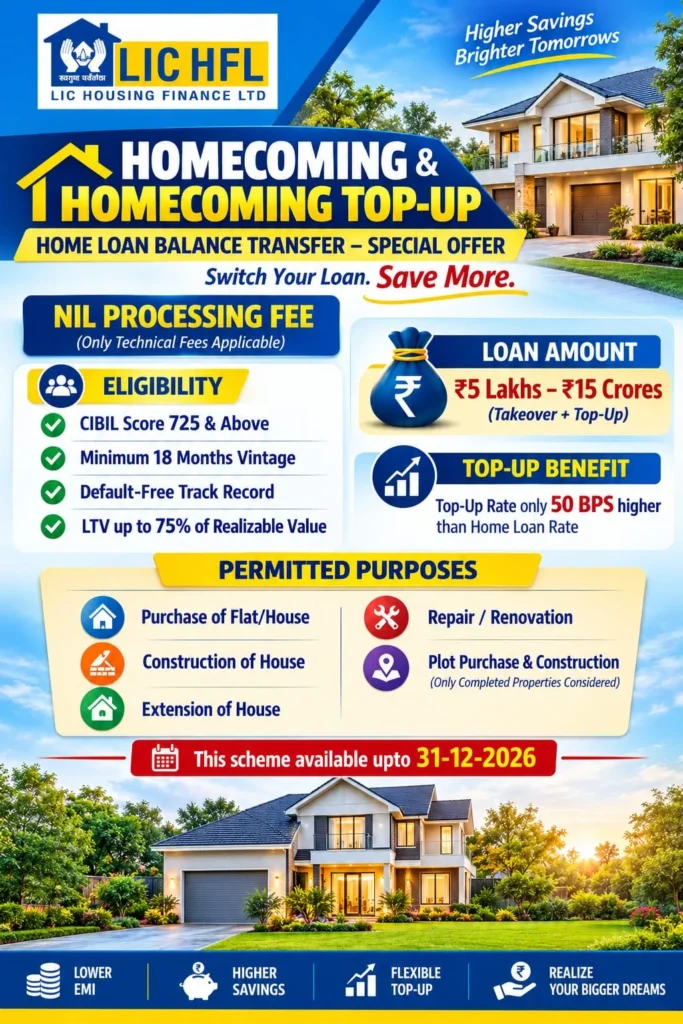
Quick answer: Homecoming is LIC HFL’s special offer for moving your home loan from another bank or housing finance company to LIC HFL. Until 31 December 2026 there is no processing fee (only the technical fee applies). You need a CIBIL score of 725 or more, at least 18 months of repayment with no defaults, and the total loan can be ₹5 lakh to ₹15 crore, up to 75% of the property’s value. Homecoming Top-Up adds extra funds at just 0.50% above your home loan rate.
By Vijay Arjun V (B.Pharm, PGDM), authorised LIC HFL DSA since 2002. Offer details as communicated by LIC HFL for the Homecoming scheme (listed under Special Offers on lichousing.com); checked 9 October 2026.
Homecoming offer at a glance
| Feature | Homecoming / Homecoming Top-Up |
|---|---|
| What it is | Balance transfer (takeover) of your existing home loan to LIC HFL, with an optional top-up |
| Processing fee | Nil; only the technical (property valuation) fee applies |
| Loan amount | ₹5 lakh to ₹15 crore, takeover plus top-up together |
| Maximum loan | Up to 75% of the property’s realisable value |
| Top-up rate | 0.50% above your home loan rate |
| CIBIL score | 725 or above |
| Repayment track record | At least 18 months on the existing loan, with no defaults |
| Who can apply | Salaried and self-employed borrowers |
| Offer valid until | 31 December 2026 |
Who is eligible?
- Your existing home loan is with another bank or HFC and has been running for at least 18 months.
- You have paid every EMI on time; the loan has no defaults.
- Your CIBIL score is 725 or more. A higher score gets a better rate; LIC HFL’s best home loan rate (from 7.15%) is for scores of 825 and above.
- The property is complete. The scheme covers loans taken for buying a flat or house, building or extending a house, repair or renovation, and plot purchase with construction, but a plot loan is considered only once the house is built.
- Your income supports the new EMI, including any top-up.
How much can you save by switching?
On a ₹50 lakh loan with 20 years left, moving from 9% to 7.15% cuts the EMI by about ₹5,770 a month, roughly ₹13.8 lakh less interest over the remaining term. Under Homecoming you do not pay a processing fee, so the switching cost is mainly the technical fee and the mortgage (MODT) charges, and you recover it sooner. Full tables in how much a balance transfer saves, or try the balance transfer calculator.
A transfer usually makes sense when the rate gap is 0.5% or more and 10 or more years are left on the loan.
How does Homecoming Top-Up work?
Along with the transfer, you can take extra money on the same property. The top-up is priced at 0.50% above your home loan rate: for example, if your home loan rate is 7.15%, the top-up would be 7.65%. That is far cheaper than a personal loan for the same need.
The transferred loan and the top-up together must stay within 75% of the property’s realisable value. Example: your flat is valued at ₹1 crore and ₹45 lakh is outstanding. The total can go up to ₹75 lakh, so a top-up of up to ₹30 lakh is possible, if your income supports the EMI.
Already an LIC HFL borrower? You do not need Homecoming; see LIC HFL top-up loans for existing customers.
How does the transfer work, step by step?
- Get your loan statement (last 12–18 months), the sanction letter and the list of documents held by your current lender.
- Send them to us with your KYC and income documents. We check your eligibility and the rate before you apply.
- LIC HFL does its credit check and the technical (valuation) and legal checks on the property.
- You get the sanction letter from LIC HFL, then ask your current lender for a foreclosure letter with the exact payoff amount.
- LIC HFL pays your old lender directly. You collect the original property documents from them and deposit them with LIC HFL.
- Your new EMI starts with LIC HFL, and the top-up, if any, is released to you.
Under RBI rules, banks and HFCs cannot charge a foreclosure penalty on floating-rate home loans to individuals, so closing the old loan should not cost you a penalty. Check your loan’s terms if it is on a fixed rate.
Documents you need
- KYC: PAN and Aadhaar of all applicants
- Income: salary slips for the last 3 months and Form 16, or ITRs and financials for the last 2 years if self-employed
- Bank statements for the last 6 months
- Existing loan: sanction letter, loan statement and list of documents from your current lender
- Property: copies of the sale deed and approvals; see property documents in Telangana
Frequently asked questions
Is the processing fee really zero?
Under Homecoming, yes: the processing fee is nil until 31 December 2026, and only the technical fee is charged. Government charges such as stamp duty on the mortgage still apply.
What if my CIBIL score is below 725?
You will not qualify for Homecoming. Improve your score first; see home loan with a low CIBIL score.
My loan is only a year old. Can I transfer it?
Not under this offer; it needs at least 18 months of repayment. Ask your current lender for a rate cut in the meantime.
Can I transfer a loan on an under-construction flat?
Homecoming considers completed properties only. Once your flat is ready and the loan fully disbursed, you can apply.
What is the deadline?
The offer runs until 31 December 2026. A transfer takes a few weeks because of the valuation, legal check and the old lender’s paperwork, so start by November.
Next step: send us your current lender, rate, outstanding amount and years left. We will tell you the new EMI, your saving and how much top-up you can get. More on home loan balance transfer in Hyderabad and LIC HFL rates for October 2026.
Sources: LIC HFL Homecoming scheme details as communicated to its DSAs (offer valid until 31 December 2026); lichousing.com balance transfer and Homecoming pages (checked 9 October 2026). Savings figures are our calculations. Terms are set by LIC HFL and may change.
Hyderabad Home Loans is run by Elite Financial Services, an authorised Direct Selling Agent (DSA) of LIC Housing Finance Ltd. We are not LIC HFL. Loans are sanctioned solely at LIC HFL’s discretion; rates and fees may change.